Crisis in the Middle East Could Cost Africa 0.2% in Annual Economic Growth
A joint policy document by four regional organizations the crisis in the Middle East having on the African economies, with growth in the continent forecast to decline by up to 0.2 percent.
The report was released by the African Union Commission (AUC), the African Development Bank Group (AfDB), the UN Economic Commission for Africa (ECA), and the UN Development Program (UNDP) in Washington, D.C., last Wednesday.
The report, entitled “Impacts of the Conflict in the Middle East on African Economies,” warns that African economies, which were slowly recovering from the severe consequences of COVID-19, the Russia–Ukraine war, and rising trade tariffs, could be hit the most by the conflict.
Kevin Urama, Chief Economist and Vice President for Economic Governance and Knowledge Management at AfDB, presented the report on the sidelines of the Spring Meetings of the International Monetary Fund and the World Bank.
He emphasized that the closure of the Strait of Hormuz had significant consequences for transport and trade.
“The report reminds us that the continent demonstrates remarkable resilience,” said Francisca Tatchouop Belobe, AU Commissioner for Economic Affairs, Development, Trade, Tourism, Industry, and Mining.
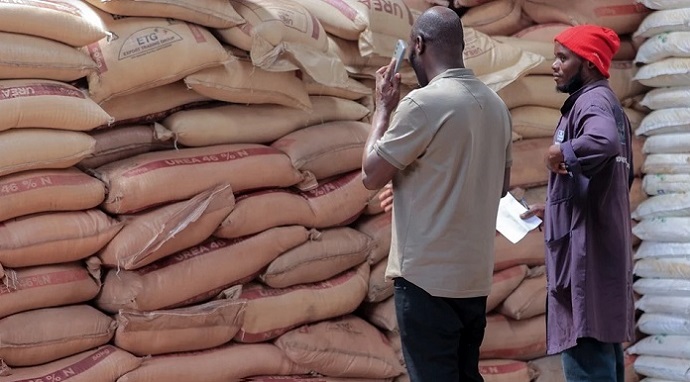
The report says the main effects of Middle Eastern conflicts on African economies include surging prices of hydrocarbons, food products, and fertilizers. They also cause disruptions to global trade, logistics, and supply chains, and made capital and foreign exchange markets volatile.
“Eighty percent of the oil imported into Africa comes from this region, as well as 50% of refined petroleum,” said Claver Gatete, Executive Secretary of the ECA.
As a result of these conflicts, 31 African countries were already experiencing currency depreciation, Gatete said.
To address the crisis, AfDB Chief Economist Urama urged African governments not to panic or take hasty decisions that could harm their fiscal balances.
The report recommends, in particular, strategic inflation management to ensure short-term price stability expectations. It cautions oil-exporting countries to adopt strict fiscal discipline by managing windfall revenues prudently, while strengthening debt-monitoring, and using energy reserves strategically.
Where fiscal space allows, it advises that temporary and targeted social protection measures be deployed to shield the most vulnerable populations from the crisis.
However, the report urges governments to avoid broad-based subsidies that could worsen long-term fiscal deficits, and to diversify sources of energy, inputs, and food supplies.
Governments are also advised to strengthen regional and intra-African trade in oil and fertilizer markets to enhance resilience; and ensure smooth inter-institutional coordination to harmonize strategic monetary and fiscal policies.
At the same time, the report calls upon development partners, multilateral banks, and development finance institutions to provide emergency support to African countries through crisis response measures and technical assistance.